Financial firms must analyse customer needs ahead of FCA targeted support proposals

The Financial Conduct Authority has concluded its consultation, ahead of new targeted support proposals to help offer financial advice to UK residents who usually miss out. According to Alistair Shipp, executive director for wealth management and private banking at Capco, companies in the sector need to analyse their customer base, and evaluate the best ways they can bridge their own advice gaps.
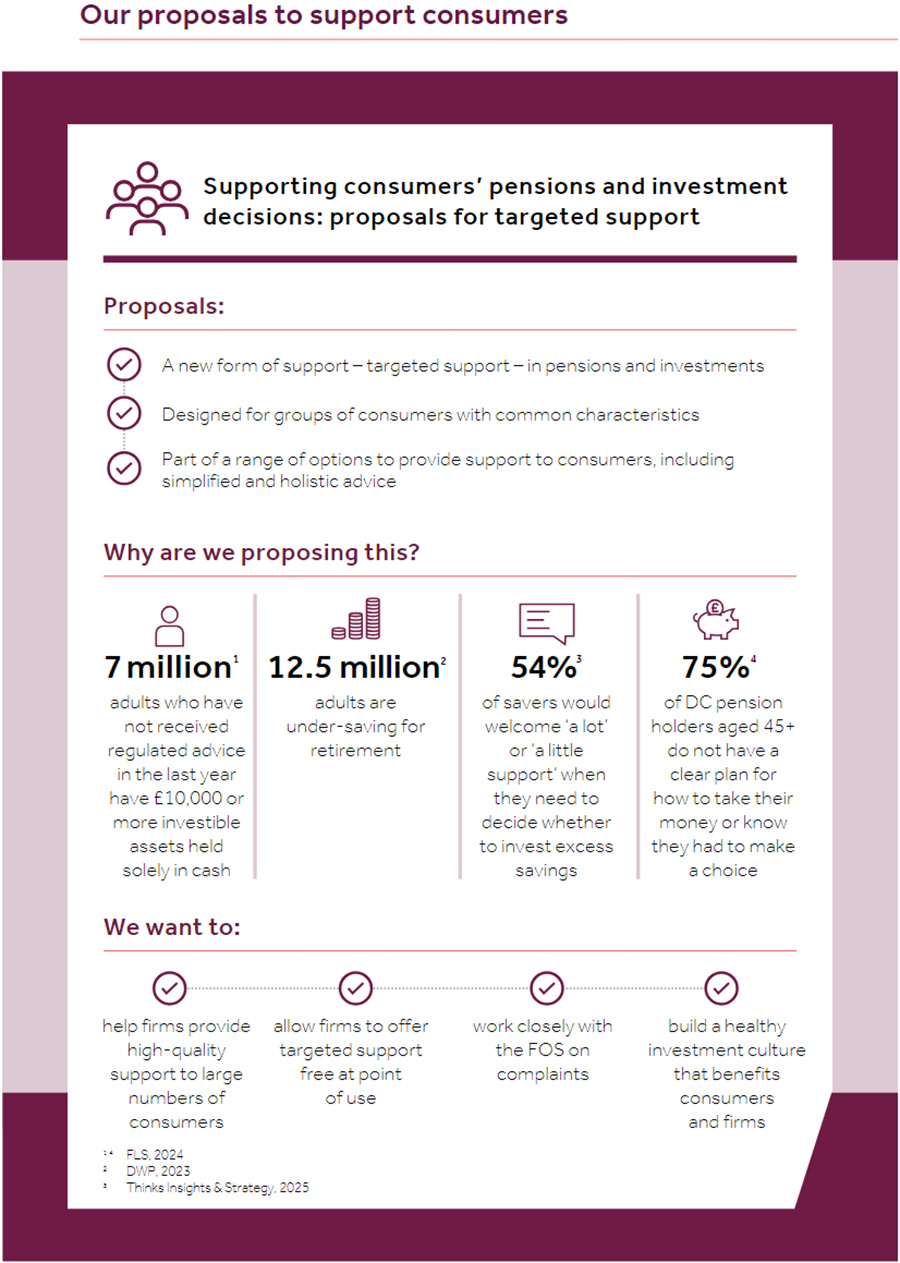
In June 2025, the Financial Conduct Authority kicked off a consultation across the financial services sector, seeking opinions for ahead of its targeted support team. According to FCA estimates, 12.5 million consumers need support in saving for retirement, while 38% of the working-age population are under-saving for the future.
Last year, 59% of adults did not use financial advice on investments, savings, pension, and retirement plans and only 9% received regulated financial advice. The FCA’s planned targeted support scheme aims at engaging with pension providers, building societies, investment firms, wealth managers, financial advice firms, and consultancy firms, working to provide a portal of financial advice to consumers that need support in their financial decisions.
In the proposal, firms would pre-define situations where a certain group of consumers would need support in, and provide “ready-made” suggestions based on these scenarios. Now, with its consultation having closed, the FCA is moving onto the next phase of policy development, to implement the targeted support scheme with investment and pension firms.
“With the FCA’s consultation on targeted support closing, it’s encouraging to see continued regulatory action to address the UK’s advice and investment gaps,” Alistair Shipp comments. “Targeted support, together with the Advice Guidance Boundary Review, goes some way in bridging these gaps by creating more opportunities for consumers to invest and providing greater clarity around advice. If firms act proactively to deliver their consumer segmentation models and scenario-based solutions, the initiative could be particularly beneficial – helping consumers take timely, appropriate action, reducing harm and supporting better outcomes.”
The Capco executive director is keen to note that targeted support is not a panacea, however. Insisting the changes should not be viewed as “the sole solution to closing the advice and investment gaps”, he adds that many consumers have complex needs, so “reducing the cost of simplified and full advice remains crucial to make it more accessible for those with less straightforward requirements”.
To that end, the broader regulatory framework, including Consumer Duty, MiFID suitability rules, and the Financial Services and Markets Act Regulated Activities Order, needs to be reviewed as well. This will ensure the FCA “encourages firms to improve consumer knowledge, clarify investment options, and support wider participation, while maintaining robust consumer protection”.
Next steps for financial services firms
Capco – now owned by Wipro – is a global management and technology consultancy specialising in financial services industry transformation. With a growing client portfolio comprising of over 100 global organisations, Capco works on initiatives for banking and payments, capital markets, wealth and asset management, and insurance clients – giving the firm’s professionals a keen insight into where firms will need to look to prepare for bridging their own advice gap.
“As it stands, it’s unlikely to be obligatory for established firms to build these new services alongside their existing offerings, so the first consideration will be whether to participate at all,” Shipp continues. “The cost and complexity of the proposals will be a key concern for firms when deciding, with the onus on firms to determine when targeted support is relevant, pre-define consumer segments and associated solutions, and ensure these solutions are suitable under Consumer Duty.”
With this in mind, Shipp says that firms considering implementing targeted support services into their offering need to begin “evaluating the business case and commercial viability now”. This includes reviewing existing systems and processes in light of the proposals to determine those that could be adapted; and identifying any additional work needed to design segmentation models, scenarios, and customer journeys.
Shipp concludes, “Alongside this, firms should also look to analyse their customer base to gauge the scale of opportunity, and reviewing risk appetite, policies, procedures, and prudential requirements to understand what changes might be necessary for successful implementation.”