UK world’s second ‘unhealthiest’ telecoms market

Kearney has launched its Global Telecom Health Index for 2026, a global benchmark of the ‘health’ of telecom sectors worldwide. According to the report, the UK is in bad need of change, finishing second-to-last in the ranking of more than 30 countries.
The UK telecommunications market is valued at over $31 billion, according to Mordor Intelligence. Shaped by recent structural consolidation – Vodafone and 3G’s 2025 merger created the largest telecoms network in the country – independent regulator Ofcom is working to ensure consumers are not ensnared by a monopoly, while 5G broadband rollouts continue to stall. As a result, while mobile networks are improving speeds, structural fragmentation in fixed lines and high capital intensity continue to challenge sector health.
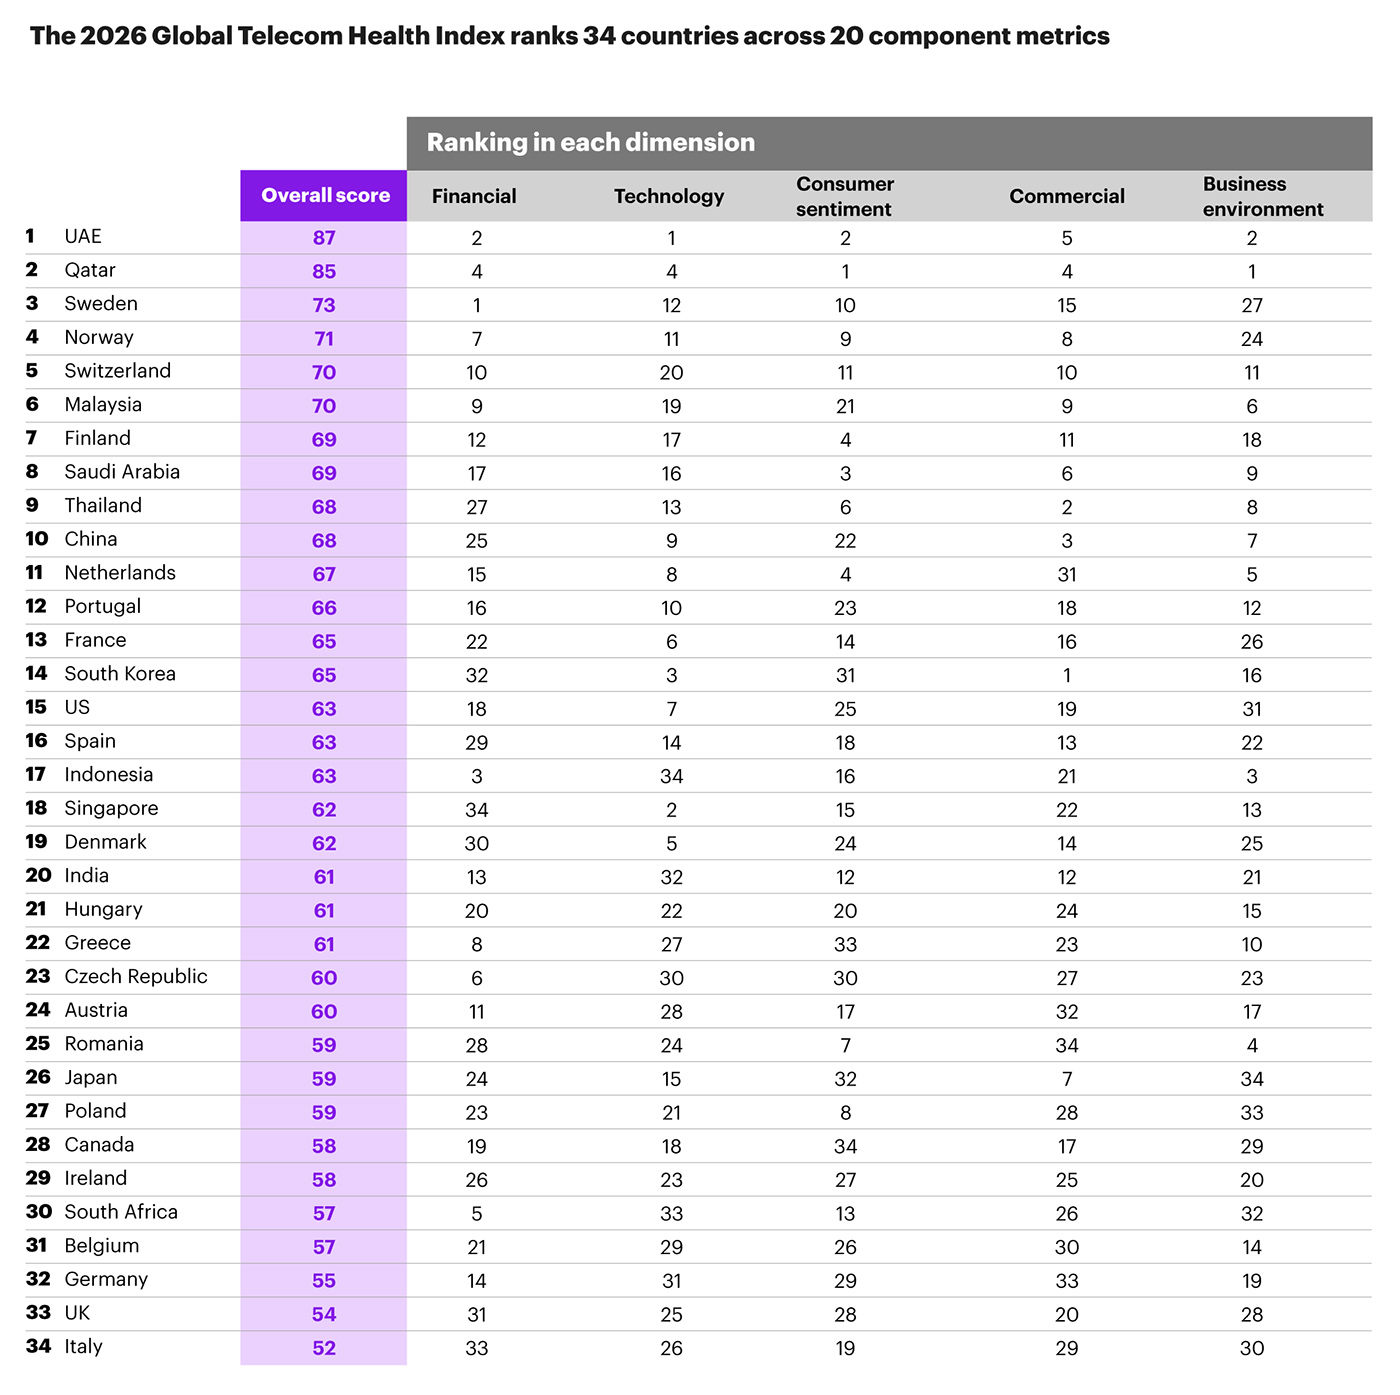
As a result, the UK has found itself close to the foot of a new 34-market benchmark by Kearney. The global strategy consulting firm evaluated telecom markets across five dimensions: financial performance, commercial ability, technology deployment, business environment and customer sentiment, using 20 metrics drawn from Kearney data, primary consumer research and trusted third-party sources – and ranked the UK at 33rd.
Size and wealth not decisive
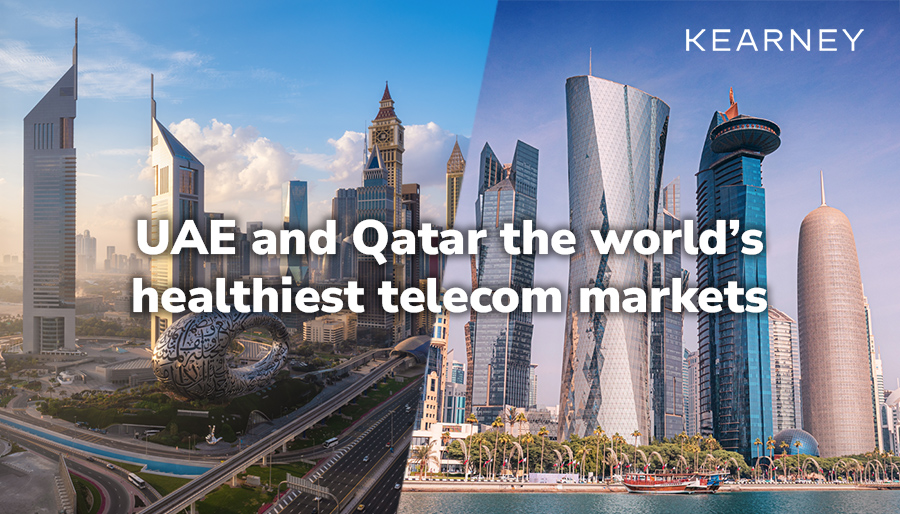
The research found there was more to telecoms health than wealth or size. Despite lower GDP per capita than many Western peers, the UAE and Qatar topped the list of many larger and wealthier markets – the US, for example, has high GDP per capita but is held back by weak customer satisfaction and mixed financial returns, despite widely available fibre and 5G.
South Korea and Singapore, both technologically advanced, sit in only the second quartile of the index, held back by customer satisfaction and returns that fall short of expectations. However, the fact that the UK failed to emulate three other European countries (Sweden, Norway, and Switzerland) in the top 10 may be more of a cause for concern – especially as it saw Britain listed far beneath the likes of Malaysia, Finland, Saudi Arabia, Thailand and China.
Indeed, only Italy performed worse in Kearney’s evaluation, while Germany was only narrowly above the UK. According to the researchers, while Germany’s market is held back by a poor rollout of fibre-optic access networks, the UK’s biggest areas of concern are technology deployment and commercial dimensions.
Where is it going wrong?
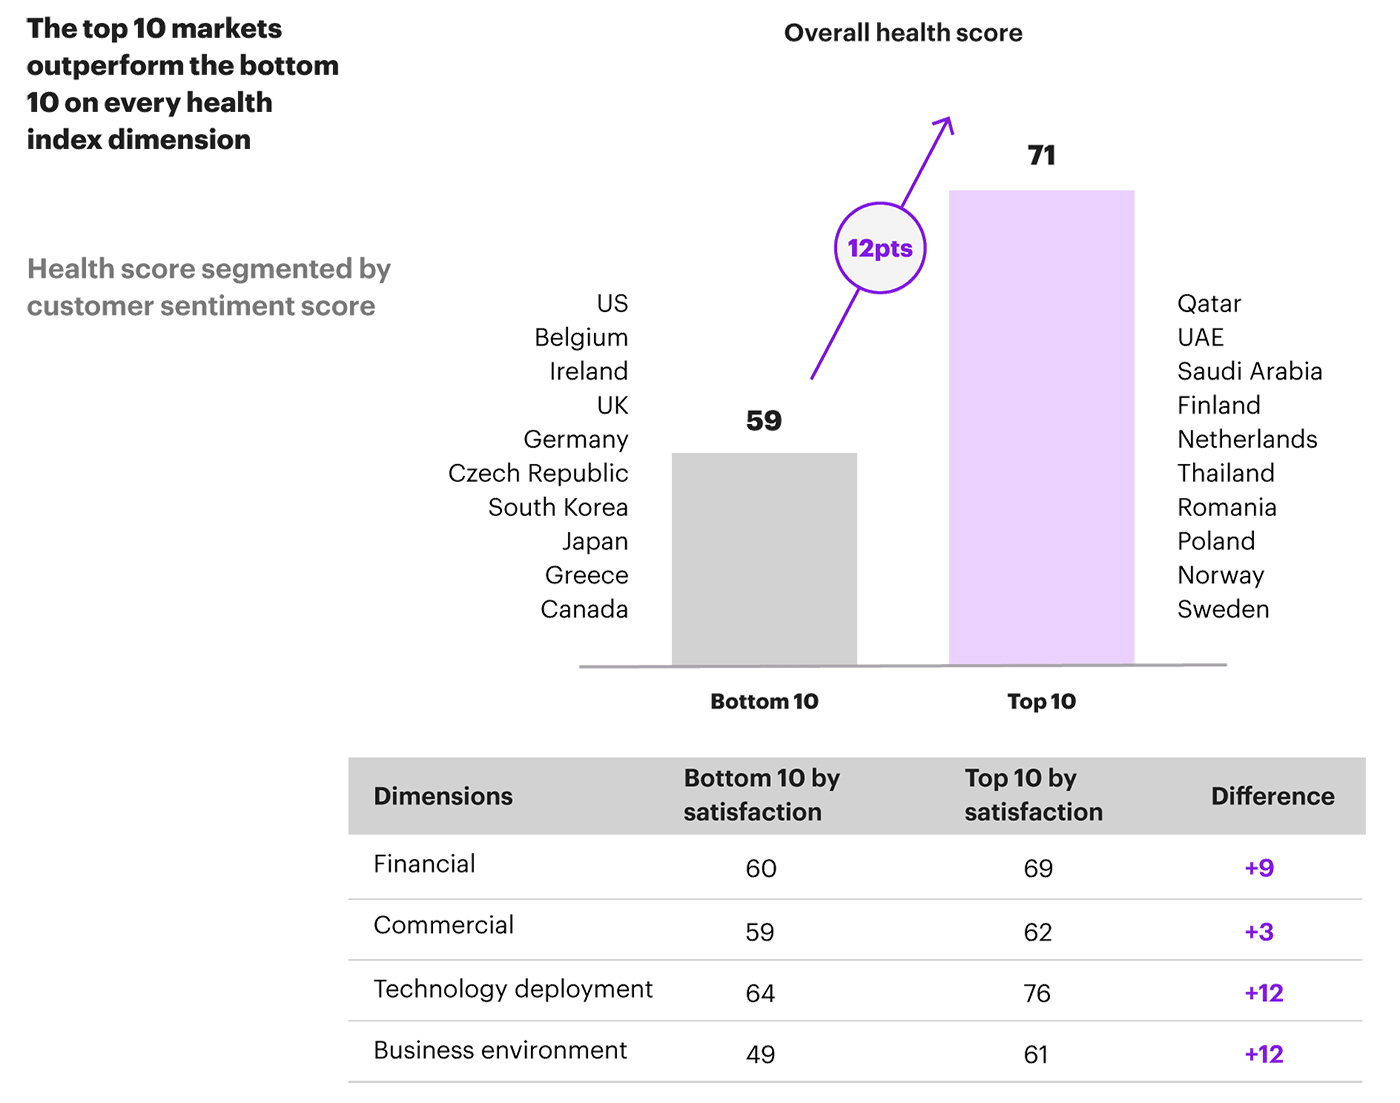
Across the board, the gap between the top-performing and lagging countries has been found to be considerable. The top 10 countries outperform the bottom 10 on every health dimension, with an average gap of 12 percentage points – driven particularly by low financial scores, poor technology deployment and, in turn, lower customer satisfaction. Canada and the UK were pointed to as examples of markets that rank particularly low on customer sentiment and also rank in the bottom half on technology deployment and commercial dimensions.
Focusing specifically on the UK, the shrinking pool of competitors means mid-contract price rises have become a norm, leading to customer discontent and a value perception gap when paying more for a service that is not seen as having improved. Government and regulatory intervention, coupled with negative press coverage, has made these increases particularly visible – so Kearney notes that operators need to make use of the opportunity now, to revisit their pricing and bundling models to drive higher value perception – and avoid further government intervention.
Reflecting on the study, the authors describe a healthy telecom sector “as a national interest of every country” around the world. “Markets that achieve this see benefits for all stakeholders, while those that do not must prioritise the shift from a potentially vicious cycle to a virtuous one. Achieving and maintaining a positive balance does not happen by chance but requires vigilance and an ecosystem with all dimensions working in sync.”