Multi-player experiences could drive new video game growth

The global video game industry is looking to kick on from a recent slump – with slowing growth resulting in layoffs across the sector. A new study from Altman Solon suggests that more inclusive, multi-player experiences could be the way forward – especially with younger players.
After a decade of historic growth, the video game industry peaked during the Covid-19 lockdown months, amid the cancellation of live events. Demand for the Nintendo Switch reached a record high in the wake of stay-at-home orders, for instance, with Nintendo’s profits surging by more than 400% in its fiscal first quarter ended June 30 2020 – especially as demand for the company’s Switch console and Animal Crossing video game skyrocketed.
The impact was not limited to Nintendo, though. During a relatively short period, the global video gaming market nearly doubled: growing from approximately $170 billion in 2019 to $244 billion in 2021. Like many other industries that made hay during the pandemic, however, this was not to last for gaming. As lockdown restrictions eased and other forms of entertainment re-emerged, the video game market stagnated, growing to only $259 billion in 2024 – ending the double-digit growth experienced in the 2010s.
Also like many industries that saw a pandemic spike in demand, this has also seen gaming in the mid-2020s characterised by a ‘corrective’ era. According to new research from Altman Solon, the option to return to public interaction, combined with a sustained decline in consumer spending power has seen player spend across all platforms tumble by a CAGR of 2% in the post-coronavirus period. Battling to maintain their short-term profit margins, many studios have resorted to layoffs, with some 38,000 being lost – reducing the number of positions in the video games industry by between 10% and 15%.
Investment activity also pulled back from the peaks of Q1 2022 – a period marked by landmark deals like Microsoft’s acquisition of Activision Blizzard, Zynga’s acquisition of Take-Two Interactive, and Bungie’s acquisition by Sony. As interest rates rose, the total number of industry deals fell by half. That may be about to change though – amid a colossal deal worth $55 billion to take Electronic Arts (EA, behind leading sports games such as EA Sports FC and Madden) private; with backing from Saudi Arabia’s sovereign wealth fund, Jared Kushener-led investment vehicle Affinity Partners, and private equity giant Silver Lake.
New trends
So, what might the trends be which have drawn such a huge outlay – and how may the industry be adapting to bring in new profits? After meteoric growth in the pandemic, free-to-play (F2P) games seem to be plateauing in popularity – raking in fees for microtransactions in the process. Consumers desperate for new experiences in lockdown flocked to them in 2021, taking their average play time to 43% of the time consumers spent on games. And while both F2P and paid games (ones consumers buy, but typically don’t need to make further purchases for), paid games have bounced back to the extent they are seeing an even higher percentage playing time than during the pandemic.
The microtransactions which made up much of the profitability of F2P games have come under fire in recent years (with some allegations that, as players would invest in ‘mystery’ packs in the hunt for sought after items, they were a form of gambling). At the same time, after the cost-of-living crisis, having spare funds constantly for F2P transactions, rather than saving for one large expense in buying a game, has become tougher – and may have further shifted this dynamic.
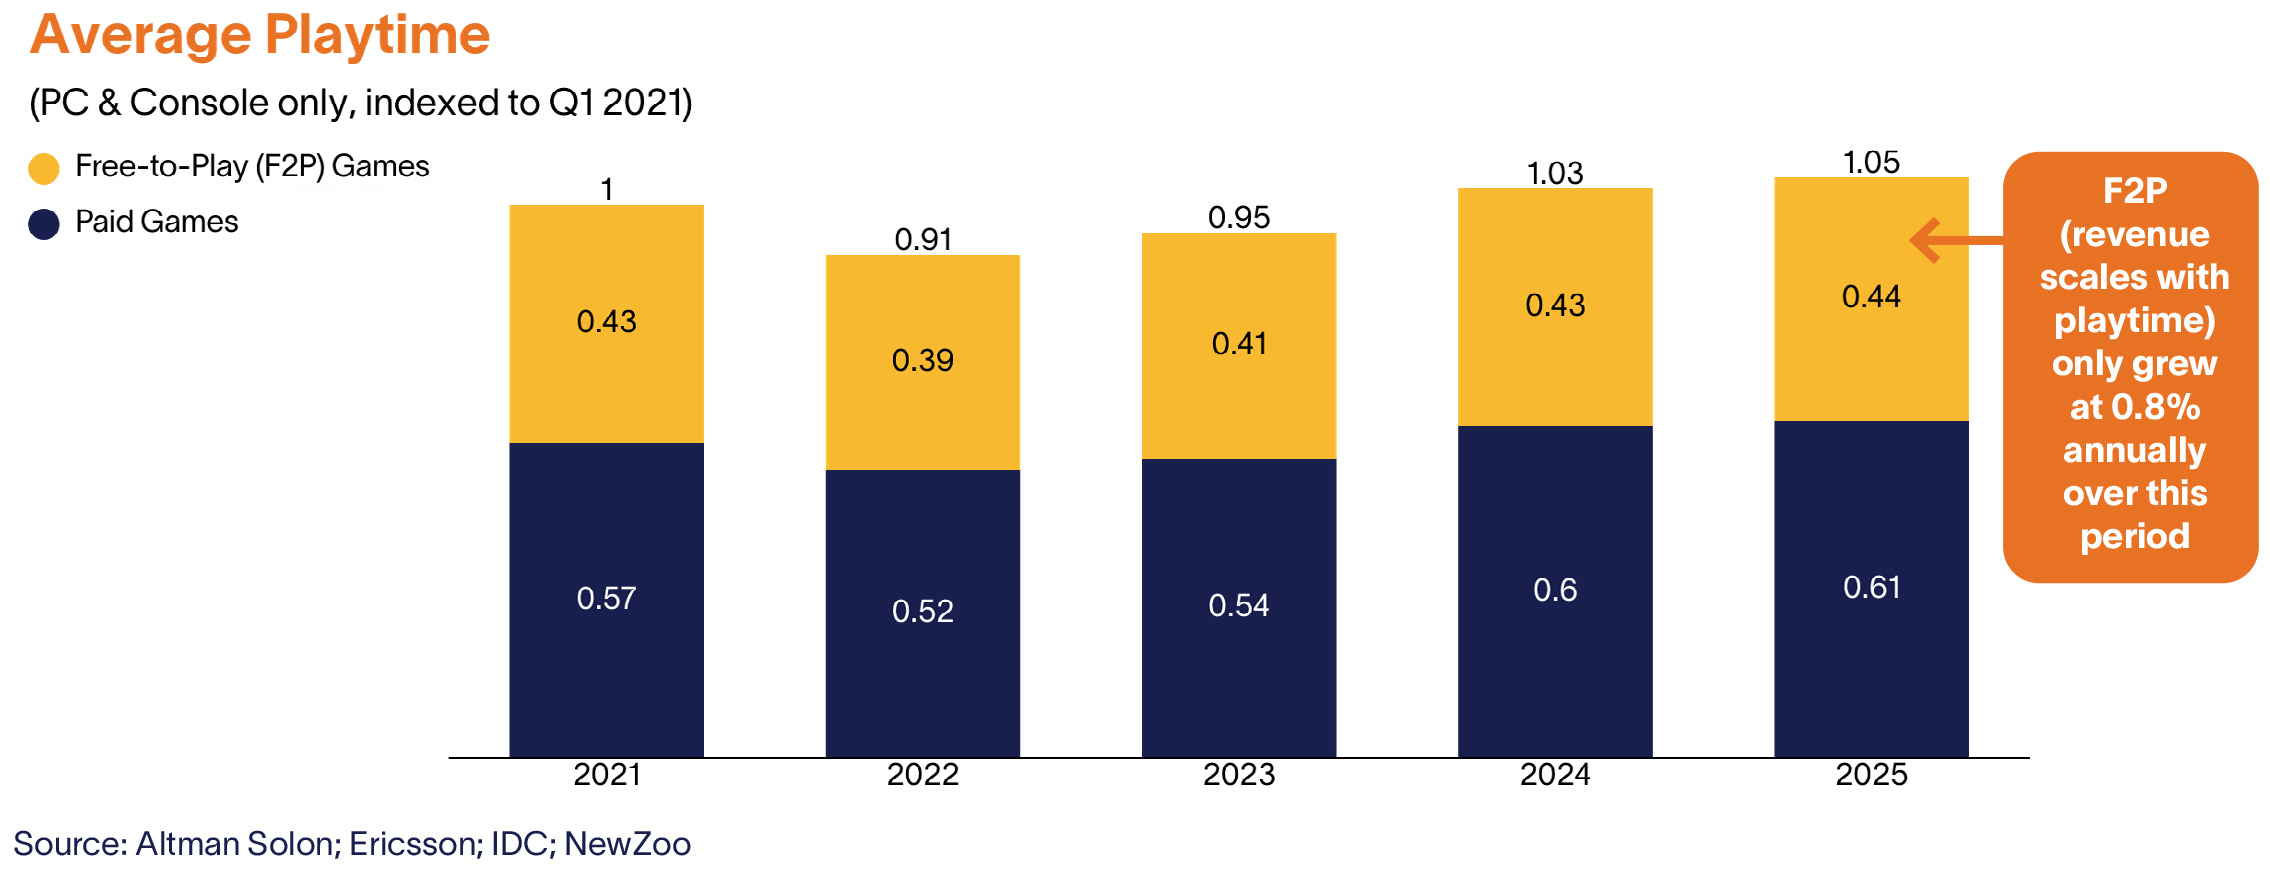
As a result, paid games have found it easier to raise their prices to historic highs in the last year. While in the early 2000s, a new video game from a leading console might have cost £30, Nintendo announced prices of $80 (around £60) at the launch of the Switch 2. Meanwhile, F2P games have struggled to adapt to integrate ad formats (for example, where users watch a short video in exchange for in-game rewards) – a long-standing part of the industry which anyone with a Duo Lingo streak over 1,000 will be well acquainted with; but one which is also largely seen as an irritation by users.
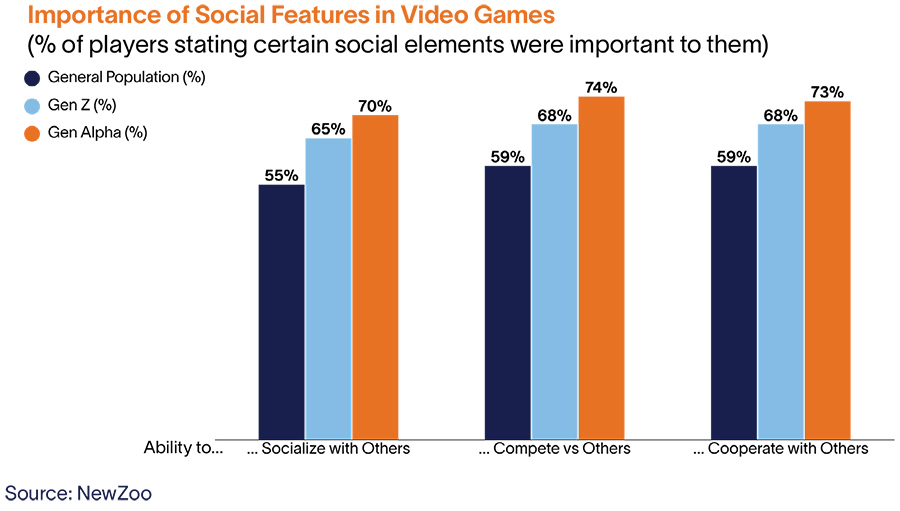
Another signifier that gamers are looking for something of substance, rather than simply cheap and quick, comes relating to multi-player games. Altman Solon finds that – contrary to long-term stereotypes, which characterise gamers as loners – there is a real appetite for local co-op or competition. While 55% of the general population play games to socialise with others, that rises to 65% in Gen Z, and 70% in Gen Alpha – suggesting opportunities in the sector reside more heavily in quality, social games – instead of short-term, ultra-single-player mobile formats.
Whether the industry can make the most of this is another thing. While Altman Solon noted that Netflix plans to roll out a party and couch co-op gaming service to stream games “like [a modernised] family board game night”, established industry players may still be set in their ways. According to another recent study from PA Consulting, while next-gen gamers want more social play, one-in-three added they do not feel represented by games, while half said they would like to see the gaming industry show how they can connect with others when they game.